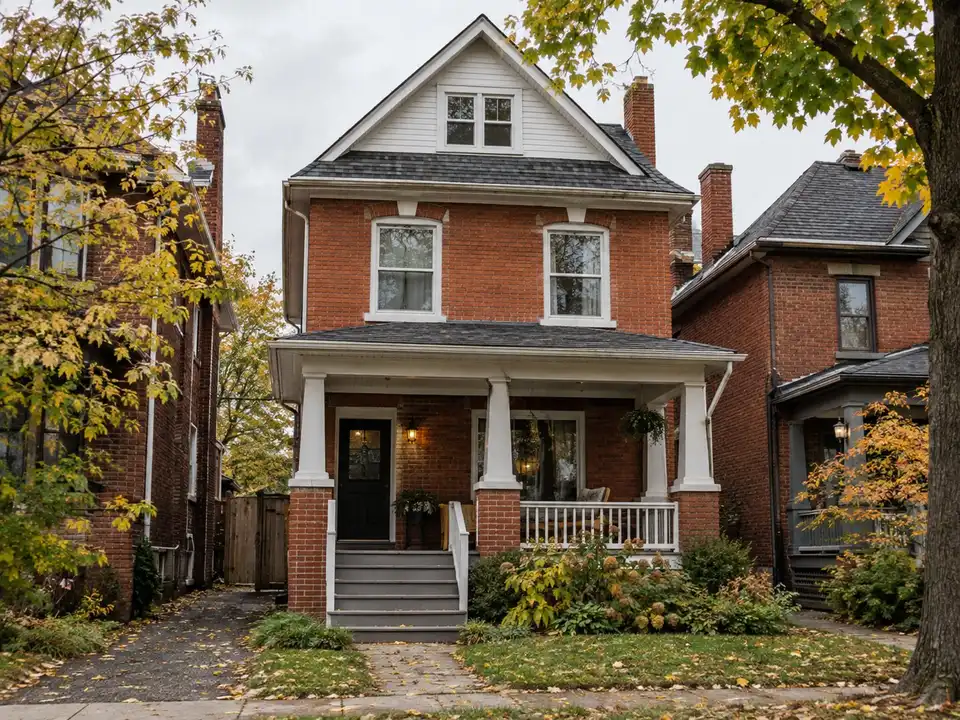
ReverseMortgageHamilton.ca explains how a reverse mortgage works for homeowners 55 and older in the lower city, the old part of Hamilton between the bay and the escarpment. This page covers what lower city homes are worth, the 2026 tax bill here, and the City programs that matter most at these prices.
Lower city homes and what they mean for the amount
The lower city has some of the oldest houses in Hamilton. Across the whole city, 32.8% of homes were built in 1960 or before (Statistics Canada, 2021 Census).
A reverse mortgage amount comes from two things: the age of the youngest homeowner and the home’s appraised value. Lower city values are below the city average. Over the 12 months to September 2026, the average sale in Hamilton Centre was $498,789, in Hamilton East $546,092 and in Hamilton West $697,533 (Cornerstone Association of REALTORS).
A lower value means a smaller amount. That’s not a reason to rule a reverse mortgage out. It’s a reason to compare it with the cheaper help the City already offers, before borrowing anything.
An older house and the appraisal
The lender’s appraiser visits the home and notes its condition. Age alone doesn’t hurt the amount. Serious disrepair can, and a lender may want a repair done before closing.
A repair you’ve already booked can sometimes be built into the mortgage, with the money held back until the repair is finished. That can pay for a roof, a furnace or new wiring. There’s more on renovating to stay in your home.
If your home is a condo
Condos qualify with every Canadian reverse mortgage lender. The building, its condo corporation and that corporation’s finances get a look too. The four lenders aren’t equally comfortable with every building, so one may say yes where another says no. Leasehold condos and co-ops don’t qualify with any lender.
The 2026 tax rate and the City’s seniors programs
The former City of Hamilton has the highest 2026 residential tax rate in Hamilton: 1.557% for urban homes with full-time fire service. The City’s own example is a home assessed at $387,100, which pays $6,028 a year (City of Hamilton, 2026 tax rates). The assessed value is the MPAC figure on your tax bill, not a sale price.
Because lower city values are modest, more homes here fit inside the City’s seniors programs (City of Hamilton, Tax Assistance Programs):
- Seniors tax rebate: a $241 credit if you’re 65 or older, your combined income is $44,568 or less, and your home is assessed at or below $505,694. A $175 utility rebate is added if you have a metered water account.
- Deferral of the tax increase: the yearly increase can wait, interest-free, until the home is sold. The same age and income test applies.
- Full tax deferral: the whole bill can wait, at 4.45% interest compounded yearly in 2026, with a $200 plus HST application fee.
The City’s deferral and a reverse mortgage are one route or the other. The deferral is a lien on the home, and anything registered against the home is paid off from the reverse mortgage money at closing. The Hamilton property tax deferral guide compares the two in plain words.
An illustrative lower city example
Here is a composite example, not a real client. An illustrative widow, 75, owns a brick house in Hamilton Centre worth about the district average of $498,789. At 75, a reverse mortgage could give her up to about $288,000.
She needs about $40,000 for a new roof and furnace. Her pension income is above $44,568, so the City’s rebate and deferrals aren’t open to her.
She takes $40,000, not $288,000, and pays interest only on the $40,000. The rest of her approval stays untouched.
She keeps paying her own taxes, insurance and upkeep, as every reverse mortgage requires. She has no required monthly mortgage payments.
When the mortgage becomes due, she can never owe more than her home is worth, so long as the property tax is paid, the insurance stays current and the house is looked after. It’s typically called the no negative equity guarantee.
What else is changing in the lower city
The Hamilton LRT route is 14 km, from McMaster University to Eastgate Square, along Main, King and Queenston (City of Hamilton, LRT). Substantial construction starts in 2028 at the earliest (The Public Record). The project doesn’t change how a reverse mortgage works or how a lender values your home.
For company and activity, the City lists two partner seniors sites downtown and in the east end: the YWCA Hamilton Active Living Centre on MacNab Street South and the Putman Family YWCA Active Living Centre on Ottawa Street North (City of Hamilton, Seniors Centres).
Who it fits in the lower city, and who it doesn’t
A reverse mortgage tends to fit lower city owners who plan to stay for years, need money for repairs or care, and earn too much for the City’s programs. It also fits owners with an old mortgage or line of credit whose payments strain a fixed income. That debt is paid off first, from the same money, at closing.
It’s usually a poor fit if you qualify for the interest-free tax deferral and only need help with taxes. It’s also a poor fit if you plan to sell within a few years, because set-up costs and early repayment charges apply. The reverse mortgage cost guide lists every one-time cost.
In the lower city, a smaller amount leaves less room for costly fees, so the lowest one-time costs matter. Richard Hopkins, Mortgage Broker, compares every reverse mortgage lender in Canada. It is free to you, and he shows you what staying and moving to a smaller place would each cost.
What Lower City homes are worth right now
Lower city prices vary by district. Over the 12 months to September 2026, the average sale was $498,789 in Hamilton Centre, $546,092 in Hamilton East and $697,533 in Hamilton West. On the Hamilton Centre average, a reverse mortgage could give up to about $252,000 at 65 and up to about $288,000 at 75. On the Hamilton West average, that's up to about $353,000 at 65 and $403,000 at 75.
| District | Average sale price | At 65 | At 70 | At 75 |
|---|---|---|---|---|
| Hamilton Centre (lower city) | $499,000 -5.0% in a year | $252,000 | $264,000 | $288,000 |
| Hamilton East (lower city) | $546,000 -7.9% in a year | $276,000 | $289,000 | $315,000 |
| Hamilton West (lower city) | $698,000 -3.6% in a year | $353,000 | $369,000 | $403,000 |
| Hamilton Mountain | $684,000 -5.0% in a year | $346,000 | $362,000 | $395,000 |
| Stoney Creek | $766,000 -5.5% in a year | $387,000 | $405,000 | $442,000 |
| Glanbrook (Binbrook, Mount Hope) | $771,000 -9.2% in a year | $390,000 | $407,000 | $445,000 |
| Dundas | $917,000 -5.3% in a year | $464,000 | $485,000 | $530,000 |
| Waterdown | $931,000 -3.3% in a year | $471,000 | $492,000 | $538,000 |
| Ancaster | $1,083,000 -6.3% in a year | $548,000 | $573,000 | $626,000 |
| Flamborough (rural) | $1,223,000 -1.8% in a year | $618,000 | $647,000 | $707,000 |
Average sale price, all home types, over the 12 months to September 2026: Cornerstone Association of REALTORS (ITSO data). Amounts use about 50.5% of the value at 65, 53% at 70 and 58% at 75, the ceilings on the market's highest-lending products. Prices and amounts are rounded to the nearest $1,000. Your own home and the appraisal set the real figure.
Lower City neighbourhoods and landmarks
The help is identical wherever you are in Lower City. A few of the neighbourhoods and places nearby:
- Corktown
- Durand
- Kirkendall
- Strathcona
- Beasley
- Westdale
- Crown Point
- Gibson
- Landsdale
- Stinson
Landmarks
- Gore Park
- Hamilton City Hall
- Hamilton Farmers' Market
- Art Gallery of Hamilton
- Dundurn Castle
- Whitehern Historic House and Garden
- Gage Park
- YWCA Hamilton Active Living Centre
How the help reaches you in Lower City
Richard is reachable by email, phone and video call, and relatives can follow along in copy. The appraiser comes to your home, wherever you are between the bay and the escarpment, and you meet your own lawyer at any lawyer's office you choose, many of them a short HSR ride along King or Main.
How Lower City homeowners use a reverse mortgage
- Renovations so you can stay home: Stairs, bathrooms and roofs in an older Hamilton house: the City and government help first, then how a reverse mortgage pays the rest.
- Paying for care at home: What publicly funded care covers in Hamilton, what families pay for on top, and how the home itself can pay for more help.